Quick take — why this matters
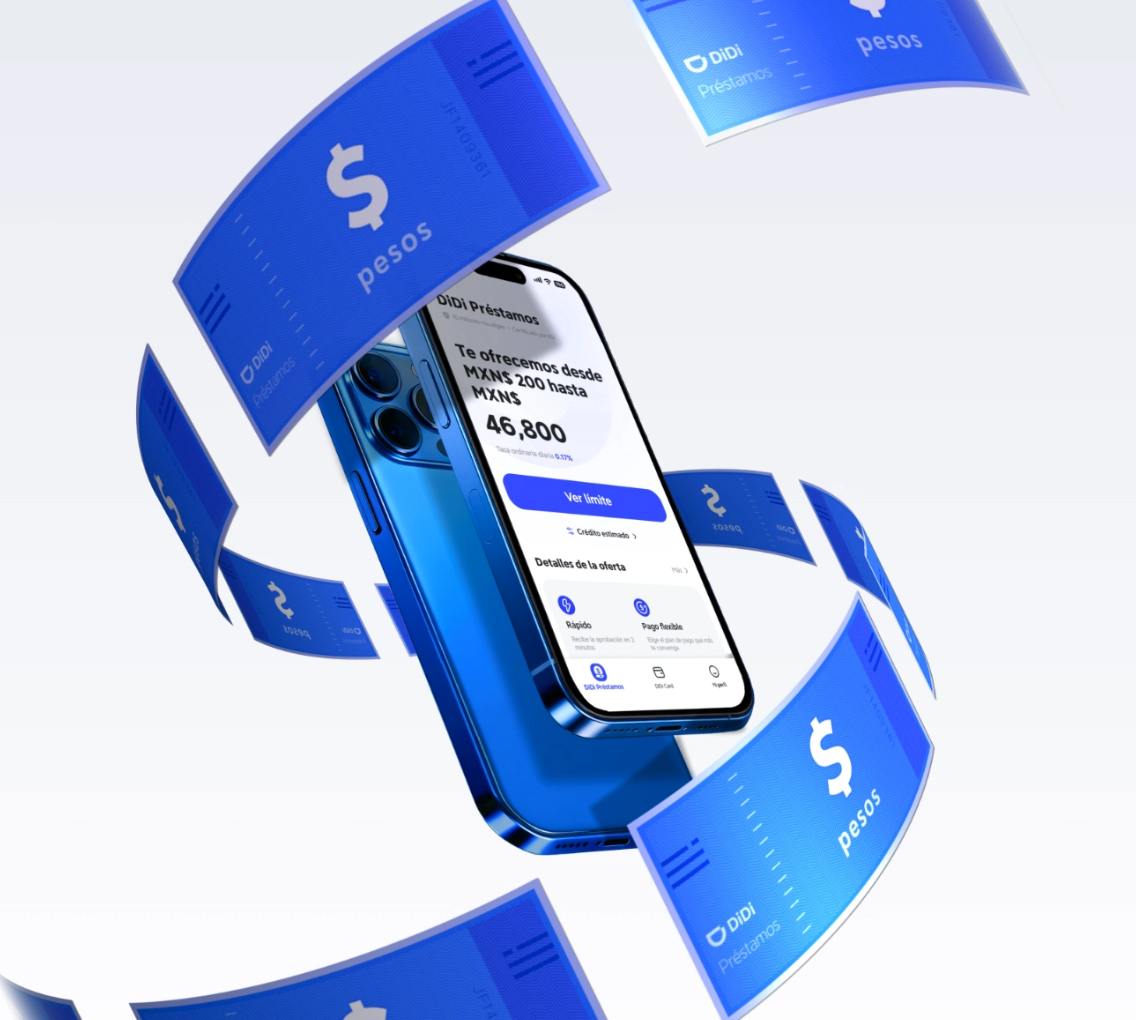
People in Mexico stopped trusting wallets the same way. Mobile apps handle payments, rewards, and small credit lines faster than plastic ever did. That shift makes the didi card worth a second look: it’s built around a mobile app, contactless payments, and instant cashback rather than long waits for statements and calls.
How DiDi Finanzas approaches everyday spending
DiDi Finanzas centers the experience on a mobile app and real-time tracking. The product focuses on cashback on rides and everyday buys, a streamlined credit line decision, and lower friction for sign-up. For drivers and riders who already use the platform in Mexico City and beyond, the integration feels natural — payments, rewards, and account management live in one place. The app emphasizes contactless use and quick notifications to keep people from missing transactions.
What traditional cashback cards still do well
Classic bank cards offer broader acceptance and often higher overall cashback tiers for categories like groceries or gas. They come with credit histories tied to established banks and sometimes additional perks: travel insurance, concierge services, balance transfer options, or separate reward networks. For heavy spenders who chase category multipliers, traditional plastic still wins on scale and established credit lines.
Head-to-head: where DiDi Finanzas beats the old guard
Here’s the plain comparison, no fluff:
– Onboarding: DiDi Finanzas is faster. You apply through the app, and approval happens quicker than many bank processes.
– Real-time control: Instant notifications and in-app freezes beat calling customer service when the card is lost.
– Relevant cashback: Rewards align with ride and local spend — more useful for urban commuters than generic points.
– Fees: Fewer surprise maintenance fees for light users. That’s a small win for people who want predictable costs.
Where traditional cards still outpace DiDi Finanzas
– Credit depth: Established banks usually offer higher credit limits and a wider set of credit-building tools.
– Travel perks and partner networks: If you value airport lounge access or airline miles, bank cards give more options.
– Long-term credit history: A card tied to a major bank can be a stronger lever for future loans and mortgages.
Common mistakes people make when choosing
Picking a card by headline cashback alone is the biggest slip-up. Folks ignore effective APR, how rewards post, and acceptance in smaller merchants. Some assume the highest percentage equals best value — but that only holds if your spend matches the reward categories. Others sign up without checking mobile app reliability or customer support hours. Those things matter when you’re traveling or disputing a charge.
Real-world anchor and context
During the COVID-19 disruption, contactless payments surged across Mexico, and Mexico City saw a big uptick in app-driven transactions as people avoided cash. That shift exposed weak points in traditional card services — slow dispute processes, delayed rewards, and clunky mobile interfaces. DiDi Finanzas jumped into that gap with a tighter app experience and faster cashback flows, which resonated with urban users and drivers who wanted simpler money management.
How to evaluate which path fits you
Look at three practical metrics before you decide:
– True cashback value: Calculate net return after fees and minimum spends, not just the headline rate.
– Liquidity and credit needs: If you need a high credit limit or loan leverage later, traditional banks often help more.
– Everyday fit: If most of your spend is app-based rides, food, and local shops, DiDi Finanzas may put cash back in your pocket faster.
Final checklist and closing rules
Golden rules: 1) Match the reward categories to your real spending. 2) Count fees and interest before you chase high rates. 3) Test the mobile app and support response once, early on — that prevents headaches later. These three checks tell you whether the convenience of an app-first product or the breadth of a bank card serves you best.
DiDi Finanzas delivers an honest, mobile-centered alternative that fixes the small, annoying problems older cards still carry — lower hassle, clearer cashback, and day-to-day control. —