Why mobile credit history matters today
Smartphone-first finance moves fast, and your credit history often decides whether you qualify for loans, better APRs, or premium services. For many users, apps are the easiest route to begin — and didi finanzas is one of the platforms designed to make that process clear and actionable. A reliable credit profile opens doors to lower interest, faster underwriting, and more negotiating power with lenders.
Context you can rely on
Global data shows a persistent gap: the World Bank reports that over one billion adults still lack access to formal financial services. That gap translates into people who have no recorded credit behavior — no credit bureau entries, no score to present. Mobile-first credit tools help bridge that divide by offering digital onboarding, reporting, and small lines of credit that build a verifiable history for future lenders.
Step-by-step: building an impeccable record on your phone
Start with identity and verification. Complete KYC promptly and accurately; mismatched documents slow down reporting and can stall credit inception. Next, pick a predictable repayment cadence. Small, on-time payments reported to bureaus move your credit score more than occasional large payments. Use a single app as your anchor for activity so your data is consistent and trackable.
When choosing features, prioritize platforms that report to credit bureaus and offer clear loan terms. Use low-cost microloans to demonstrate payment behavior before applying for larger credit. Track utilization: keeping credit utilization low signals strong risk management to algorithms during underwriting.
How DiDi Finanzas app helps — practical functions
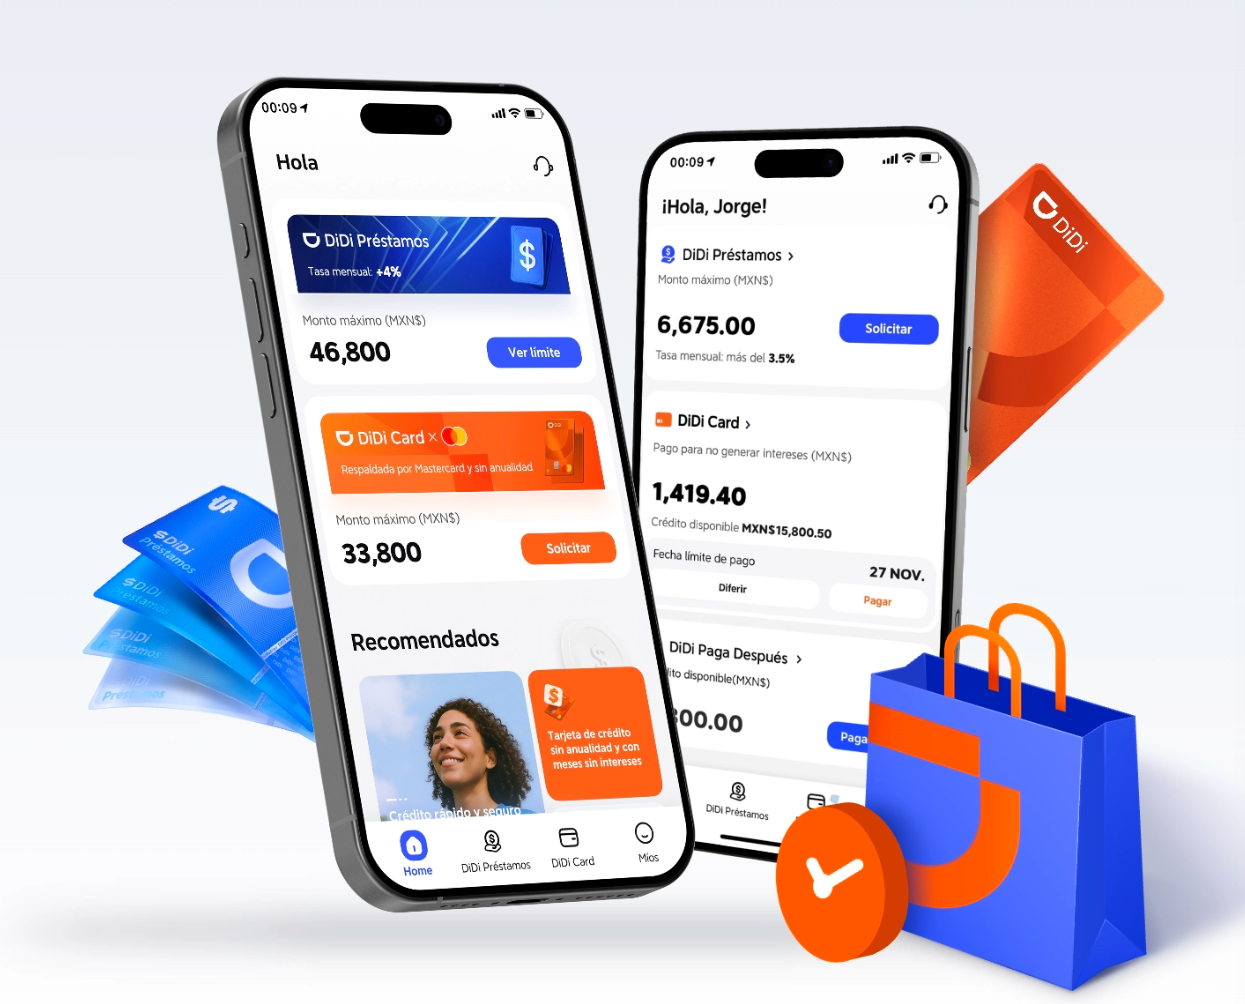
didi finanzas app bundles onboarding, loan management, and repayment reminders in one interface. The app’s transaction history and automated receipts create an auditable trail that lenders can use when calculating creditworthiness. Notifications prevent missed payments; payment plans and amortization schedules show you exactly how much principal and interest remain — useful for watching effective APR and improving your score incrementally.
Common mistakes to avoid
Many users assume any payment counts equally; it doesn’t. Avoid opening multiple small lines at once — hard inquiries and short-term spikes in utilization can temporarily depress a score. Ignore temptation to skip the reporting step: if your app or lender doesn’t report to a bureau, your disciplined payments won’t show up. Finally, keep profile data up to date; old addresses or job entries can trigger delays in identity checks.
— Keep your accounts tidy. Closing the wrong account can shorten your credit history and hurt your score.
Alternatives and when to use them
If you prefer a bank-led route, traditional institutions still offer steady reporting and sometimes higher credit limits. Peer-to-peer platforms can be faster but may not report broadly. Use microloan apps to establish history, then graduate to a bank or secured card to diversify account types — that mix improves your credit depth and reduces concentration risk.
Summary of best moves
Start with verified identity, choose one reporting app, keep utilization low, and make punctual payments. Track effective APR on any credit instrument and opt for options that explicitly report to credit bureaus. Small, consistent wins compound into a strong profile over months, not years.
Three golden rules for evaluating tools and strategies
1) Reporting Breadth — Confirm the platform reports to national credit bureaus. That’s the foundation of any visible credit history. 2) Transparency of Terms — Clear repayment schedules and APR disclosures protect you from hidden costs and improve planning. 3) Behavioral Signals — Look for tools that support on-time payments, give reminders, and provide amortization views; they directly influence the underwriting models lenders use.
These metrics let professionals and everyday users judge a tool’s real value — and they point to predictable outcomes when applied consistently.
DiDi Finanzas fits naturally into this flow by making reporting and repayment visible — a straightforward path from initial microloan to a robust credit profile. —